


The Rest of the World Is Up. India Is Down. What Is Actually Going On?
 17-Oct-2026
 2 mins read
Trending Now
-
Turtlemint Fintech Solutions IPO GMP, Open Date, Price Band, Issue Size 18-Jun-2026
-
.jpg)
SpaceX IPO: Elon Musk Becomes World's First Trillionaire — Key Facts Explained 13-Jun-2026
-
Zepto IPO, Open Date, Issue Size, Price Band and UDRHP Filed 12-Jun-2026
-
Shah Metacorp Rights Issue May 2026 Details, Record Date, Issue Price 26-May-2026
-
Jio Is Going Public. Here's What That Actually Means for You 11-May-2026
-
Parle Products IPO: India’s Most Iconic Biscuit Brand Going Public? 30-Apr-2026
-
Gujarat Cotex Rights Issue 2026 Details, Record Date, Issue Price 27-Mar-2026
-
.jpg)
Avi Polymers Rights Issue 2026 Details, Record Date, Issue Price 11-Feb-2026
-
D & H India Rights Issue 2026 Details, Record Date, Issue Price 05-Feb-2026
-
Avasara Finance Rights Issue 2025 Details, Record Date, Issue Price 29-Dec-2025
Why Indian Stock Markets Are Falling in 2026 Despite Global Market Gains
2026 has been a confusing year for Indian investors.
Not because the economy is doing badly, it is not. GDP is growing at 7.8%. Corporate earnings are healthy. SIP inflows hit a record ₹32,490 crore in September. The banking system is well capitalised. Domestic consumption is holding up.
And somewhere in between those facts, a genuinely important story is hiding.
The Economy and the Market Are Telling Different Stories
If the economy is doing well, why is the market falling?
The answer is that stock markets don’t move on how an economy is doing today. They move on where global capital is flowing and right now global capital has found something more attractive than Indian equities.
To understand what that something is, you need to understand what has happened globally in 2026.
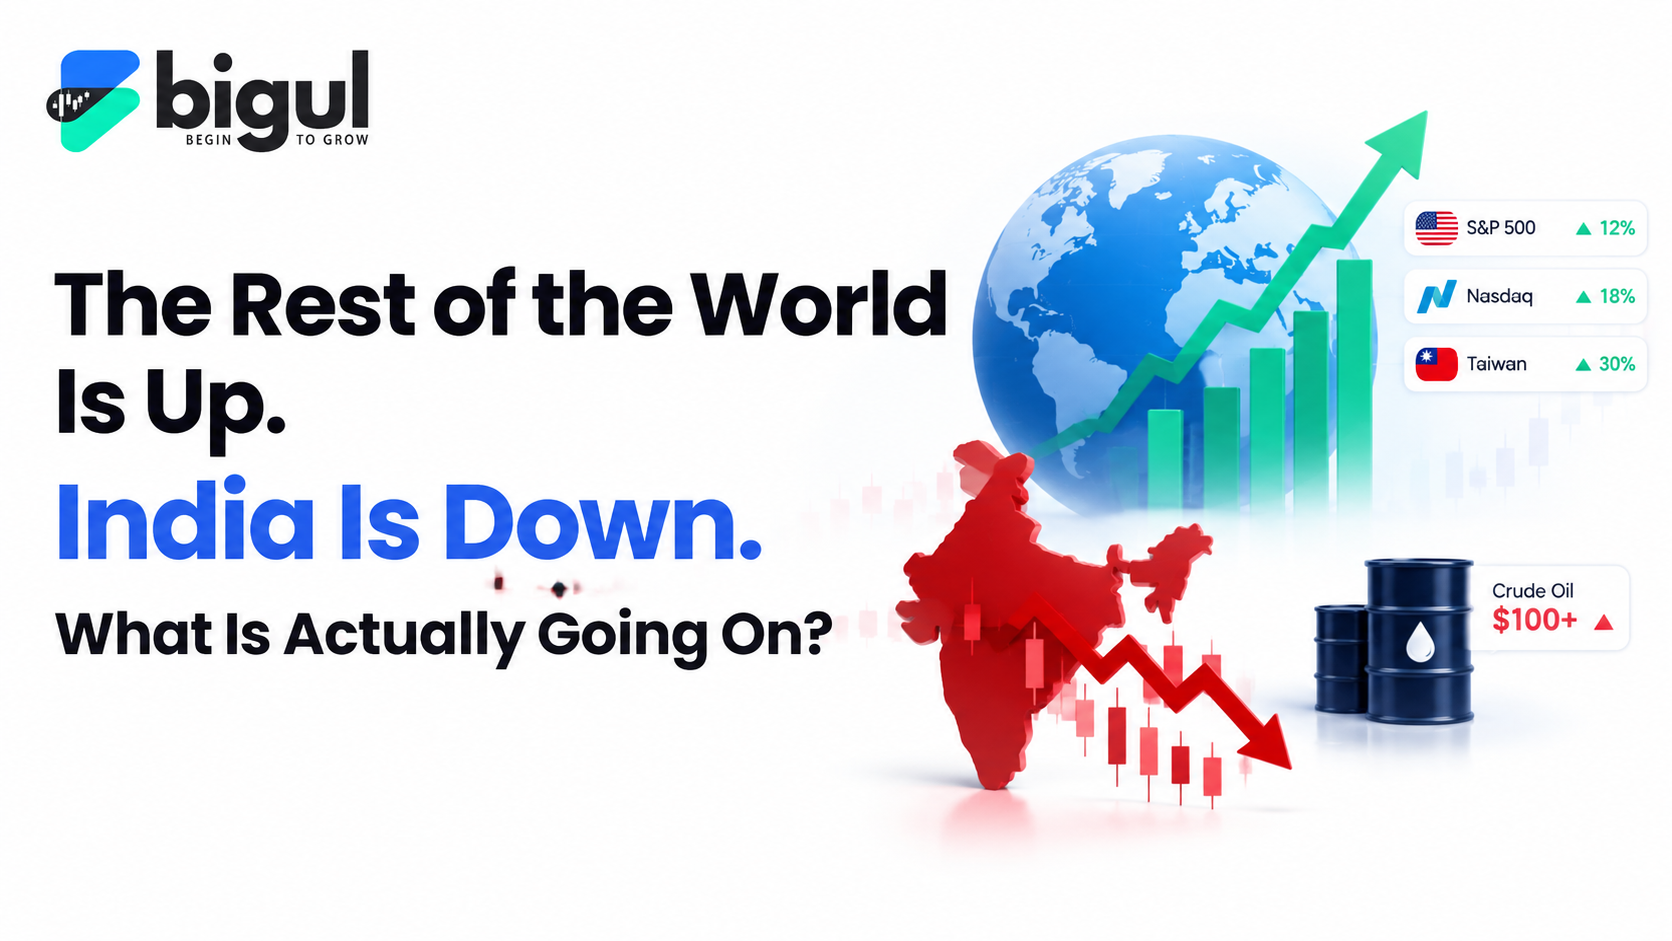
Global markets have had an extraordinary year. The S&P 500 is up 12%. The Nasdaq is up 18%. Taiwan’s market is up 30%. Every one of these rallies has been driven by the same underlying force.
Artificial intelligence.
Not AI as a concept. AI as a hardware business.
Every time you open AI, physical chips make that response possible. Nvidia designs those chips. TSMC in Taiwan manufactures them. Samsung and SK Hynix in South Korea supply the memory. Meta, Google, Amazon and Microsoft are together planning to spend over $400 billion building AI infrastructure next year.
Global markets have rallied 30 to 150% since India’s September 2024 peak — driven almost entirely by this narrow, concentrated AI hardware rally that has favoured Taiwan, South Korea and the United States. global markets rallied up
India’s IT companies — TCS, Infosys, HCL Tech benefit from AI as service providers helping companies implement it. But it is not the hardware business that global capital is currently rewarding at extraordinary multiples.
The money didn’t disappear from emerging markets.
It moved specifically to the countries sitting on the AI hardware supply chain.
And Then Three Things Hit India Simultaneously
AI rotation alone might have been manageable.
But three other forces arrived at the same time and all of them pointed in the same direction.
US bond yields crossed 5%.
The US 10-year Treasury yield hit 5.3%, its highest level in nearly two decades.
That number changed the calculation for every global fund manager.
If you can earn 5.3% on US government bonds: risk-free, dollar-denominated, with zero uncertainty then investing in Indian equities needs to offer a compelling return premium to justify the additional risk.
For most of 2024, India’s growth story made that premium obvious. At 5.3% US yields; the math stopped being so clear.
Foreign institutional investors have offloaded over ₹4 lakh crore worth of Indian equities in 2026, the largest annual FII outflow in India’s history. Indian Markets slide 15%
This is rational capital allocation by funds doing exactly what fund managers are supposed to do. Going where the risk-reward is most compelling.
Crude oil crossed $100.
India imports more than 85% of its crude oil requirements.
When Brent crosses $100 — four things happen in quick succession. The import bill rises. The current account deficit widens. The rupee weakens — because more dollars need to leave India to pay for oil. And inflation climbs — because energy costs flow through into almost every product and service.
The RBI responded on October 7 with the first rate hike since February 2023 — taking the repo rate from 5.25% to 5.5%.
Higher rates mean higher borrowing costs for companies which means lower earnings growth expectations, which means valuations compress. Real estate, auto and consumer finance felt this most immediately.
Why Global Markets Did Not Fall With India?
The answer is that the specific combination of pressures hitting India is not hitting most other markets with the same force.
The US is largely energy independent. High oil prices help American energy companies rather than hurting the broader economy the way they hurt India.
US technology companies are posting revenue growth of 40 to 50% driven by AI demand. That growth story is powerful enough to absorb rate pressure, which is why the Nasdaq is up 18% even in a high-rate environment.
Europe is mixed but doesn’t face India’s specific combination of oil import dependence and FII exit dynamics.
What Is Actually Holding India Together?
While FIIs were selling; Indian equity mutual funds posted 63 consecutive months of positive inflows. US equity mutual funds saw net outflows during the same period. Indian equity funds saw net inflows of ₹1,28,897 crore.market recovery
In March 2026 when FIIs sold ₹1,17,775 crore in a single month, domestic institutions absorbed ₹1,42,960 crore. The Nifty fell 11.3% but it did not collapse.
Domestic institutional investors net-purchased ₹6.8 lakh crore in Indian stocks throughout 2026 providing the floor that prevented a steeper decline.
Crore of Indian investors each contributing ₹500 or ₹5,000 into a SIP every month collectively became the most stabilising force in India’s equity market at exactly the moment it needed stabilising most.
Five years ago, this kind of domestic institutional capacity simply did not exist. Today it does and that changes the nature of how Indian markets respond to global pressure.
Three Things to Watch
Nobody can tell you exactly when this reverses.
But three things will determine when it does.
US bond yields stabilising or falling from 5.3%. When the premium that US bonds offer over Indian equities narrows — global capital becomes more willing to take emerging market risk again.
Crude retreating from $100. Every dollar that Brent falls reduces pressure on the rupee, the current account deficit, and domestic inflation simultaneously.
Indian corporate earnings growing into current valuations. At a Nifty PE of approximately 19.3 — valuations have already corrected significantly from the January peak. The question is whether earnings deliver the growth that justifies even these levels.
But all three have happened before. After every comparable period in Indian market history — 2008, 2011, 2015, 2018, 2020 — they shifted. And the market recovered.
Visit : Open A Demat Account Today with Bigul